Geekzone: technology news, blogs, forums
Guest
Welcome Guest.
You haven't logged in yet. If you don't have an account you can register now.


View this topic in a long page with up to 500 replies per page Create new topic
1 | ... | 169 | 170 | 171 | 172 | 173 | 174 | 175
dafman
4173 posts

Uber Geek
+1 received by user: 2784

Trusted
Subscriber

  #3470669 15-Mar-2026 19:15
Send private message

mattwnz:


Australia’s house prices have continued to increase since Covid and they haven’t had the same housing crash


… yet.


mudguard
2396 posts

Uber Geek
+1 received by user: 1303


  #3470691 15-Mar-2026 21:27
Send private message

tweake:


the problem is $600k is now an entry level house and median income is ~$70k. so it takes 2x people both on median income. so yes, 150k can service it at 8% but thats entry level house, not average house. average fhber is ~40 years old, almost at peak income and income will be declining for half the loan. loose your job at 55 and it can be a real struggle to get another due to agism, and you still have half the mortgage to go.


The only saving grace is if first home buyers are now 40, they'll have a grunty deposit if they're in Kiwisaver from age 20. Still not saying it's a picnic. Your average 25 year old will struggle to save 20% by that age not to mention being in a stable enough relationship to buy. 


But income should really keep going up. And agree, can't help the job market but that's probably not that different to other blips in the past twenty years. I'm not sure how you can legislate it away. You could set DTI to three, and that would fix it, but not for at least a generation.


cddt
2181 posts

Uber Geek
+1 received by user: 2146


  #3470702 16-Mar-2026 06:18
Send private message

mudguard:


The only saving grace is if first home buyers are now 40, they'll have a grunty deposit if they're in Kiwisaver from age 20. Still not saying it's a picnic. Your average 25 year old will struggle to save 20% by that age not to mention being in a stable enough relationship to buy. 


But income should really keep going up. And agree, can't help the job market but that's probably not that different to other blips in the past twenty years. I'm not sure how you can legislate it away. You could set DTI to three, and that would fix it, but not for at least a generation.


25 is a better age to have children than 40 though. Time and health aren't infinite. 


Re income - productivity growth has been dire for the last three decades and still getting worse. 


mudguard
2396 posts

Uber Geek
+1 received by user: 1303


  #3470704 16-Mar-2026 07:10
Send private message

cddt:


mudguard:


The only saving grace is if first home buyers are now 40, they'll have a grunty deposit if they're in Kiwisaver from age 20. Still not saying it's a picnic. Your average 25 year old will struggle to save 20% by that age not to mention being in a stable enough relationship to buy. 


But income should really keep going up. And agree, can't help the job market but that's probably not that different to other blips in the past twenty years. I'm not sure how you can legislate it away. You could set DTI to three, and that would fix it, but not for at least a generation.


25 is a better age to have children than 40 though. Time and health aren't infinite. 


Re income - productivity growth has been dire for the last three decades and still getting worse. 


Yep, I think we all know that children are easier to have the younger you are. My income was pretty average at 25, a couple of stints at university etc. There was no way I was buying at 25. 


The bottom line is in that the space of probably a generation and a bit we've gone from a reasonable DTI most likely based off one income, to one that's hugely out of whack on two incomes.


tweake
2787 posts

Uber Geek
+1 received by user: 1217


  #3470954 16-Mar-2026 17:38
Send private message

mudguard:


The only saving grace is if first home buyers are now 40, they'll have a grunty deposit if they're in Kiwisaver from age 20.


not really. if they have the ability to have a grunty deposit by age 40, they would have bought a house at age 30. most people don't wait to buy a house, they buy as soon as they can. the average age of fhber's is not by choice, its how long it takes to save the minimum they need. 


here is the other issue, the sooner or better they save for a deposit, the higher the house prices will go. the more money fhbers have, the higher the prices will go up to take that advantage away. eg if parents start giving money to the kids to help buy a house, then that will become mandatory for everyone. this is why the increases in kiwisaver is such a croc, its a mandatory house deposit savings scheme to boost house prices and those fhbers will loose out. its simply sends more of their income to someone else.


tweake
2787 posts

Uber Geek
+1 received by user: 1217


  #3470955 16-Mar-2026 17:41
Send private message

cddt:


25 is a better age to have children than 40 though. Time and health aren't infinite. 


Re income - productivity growth has been dire for the last three decades and still getting worse. 


its a big reason why many are choosing not to have kids. can't afford kids and a home. 


why chase productivity when your house is your income, all paid for by the next generation.


Shop now for Lego sets and other gifts (affiliate link).
mudguard
2396 posts

Uber Geek
+1 received by user: 1303


  #3470988 16-Mar-2026 19:52
Send private message

tweake:


This is why the increases in kiwisaver is such a croc, its a mandatory house deposit savings scheme to boost house prices and those fhbers will loose out. its simply sends more of their income to someone else.


So take your pick. If you changed the rules for Kiwisaver tomorrow (allowing those already in to be unaffected) do you think it would change anything?


I used Kiwisaver for exactly that. Put away 8% for most of my time in it (from when it started) with the express goal of taking it out. If it hadn't been an option I'd probably have put the bare minim run for the government credit.


I'd say despite the prices increasing I'd say more people have a chance to buy than if left to their own devices. I'm not sure how you would work it out. But my experience in the mortgage industry is that it's often the only saving some can do.


From memory my deposit was roughly 30% savings and the rest Kiwisaver. I'd have to go back and work out how much of 70% was my own salary. 


mudguard
2396 posts

Uber Geek
+1 received by user: 1303


  #3470989 16-Mar-2026 20:06
Send private message

tweake:


cddt:


25 is a better age to have children than 40 though. Time and health aren't infinite. 


Re income - productivity growth has been dire for the last three decades and still getting worse. 


its a big reason why many are choosing not to have kids. can't afford kids and a home. 


why chase productivity when your house is your income, all paid for by the next generation.


I think the maths is in this thread. It's not as black and white as sitting and let the value climb.


Hypothetically, if the value doubles every decade, or whatever it is, a mortgage still needs to be paid for that decade plus the usual costs (which to be fair, could be paid by rent as well)


Take $600,000 over thirty years at 8%.


$480,000 after 20% deposit.


After ten years you'll still owe $421,000 having paid the same amount to the bank.


So maybe you sell up then for $1M. And buy for $1.5M, now with a $900K loan. Most likely it would be another thirty year term but the clock is ticking as while they won't say, banks won't want to lend past 70.


Another ten years go by and you still owe $790K having spent another $800k.


And this is assume what you're getting at. Sell the last one for $3M, buy in another part of the country with no mortgage and money in the bank. 


tweake
2787 posts

Uber Geek
+1 received by user: 1217


  #3470996 16-Mar-2026 20:08
Send private message

mudguard:


So take your pick. If you changed the rules for Kiwisaver tomorrow (allowing those already in to be unaffected) do you think it would change anything?


would it change anything today, not much. will it change whats happens in 20 years, hell yeah.


i think it needs to be viewed in context of what else is happening. eg luxon wanting to open up ks to rents, RE industry wants it open up to investment housing, opening it up for "rural" etc. its a big fat pool of money that everyone wants, i would be surprised if ks even exists in 10 years time.


as its often the only saving some people do, i would like to see ks return to its roots and only be a retirement fund, because they are going to need it.


tweake
2787 posts

Uber Geek
+1 received by user: 1217


  #3470997 16-Mar-2026 20:18
Send private message

mudguard:


And this is assume what you're getting at. Sell the last one for $3M, buy in another part of the country with no mortgage and money in the bank. 


thats exactly how its done. i've got plenty of ex auckland retires near me who sold their big auckland house and retired in a small farm town. thats their version of ks.


but my issue is who is paying for that? the price only "doubles every ten years" because you can force ("helping") the all important fhber to overpay. we have generations who live(ed) lifestyles well above their work input by passing the cost onto the next guy. 


mudguard
2396 posts

Uber Geek
+1 received by user: 1303


  #3471002 16-Mar-2026 21:01
Send private message

tweake:


mudguard:


And this is assume what you're getting at. Sell the last one for $3M, buy in another part of the country with no mortgage and money in the bank. 


thats exactly how its done. i've got plenty of ex auckland retires near me who sold their big auckland house and retired in a small farm town. thats their version of ks.


but my issue is who is paying for that? the price only "doubles every ten years" because you can force ("helping") the all important fhber to overpay. we have generations who live(ed) lifestyles well above their work input by passing the cost onto the next guy. 


Yep and that sucks for the locals. I have friends who have relocated and taken their big city incomes with them. But the exodus out of Auckland won't last forever. 


Doubling in price looks optimistic. 


Reserve Bank has had house inflation at 5.2% for the last decade. General goods inflation at 3.1%


And wages at 4.3% so it's not that out of whack. You will never pay the same in real terms for an object. 


So at minimum housing will always increase. It's just relative to wages and other items. I still don't know what the answer is, I'm not really worried what is done to Kiwisaver as long as people have the choice. IE if people signed up thinking they could use it for a deposit then let them.


More of a worry is changing demographics. Houses will be cheap then. Everyone will want to downsize and there's no one to sell to. 


Want to support Geekzone and browse the site without the ads? Subscribe to Geekzone now (monthly, annual and lifetime options).
elpenguino
3651 posts

Uber Geek
+1 received by user: 3071


  #3471017 16-Mar-2026 23:02
Send private message

tweake:


cddt:


25 is a better age to have children than 40 though. Time and health aren't infinite. 


Re income - productivity growth has been dire for the last three decades and still getting worse. 


its a big reason why many are choosing not to have kids. can't afford kids and a home. 


why chase productivity when your house is your income, all paid for by the next generation.


Low birth rates are standard all over the world so there's bigger factors at play.


Women are more educated than ever before and you don't have to be a genius to realise you have more interesting life options than popping out babies.


Graph from https://en.wikipedia.org/wiki/List_of_countries_by_total_fertility_rate


Knowledge is knowing that a tomato is a fruit, Wisdom is knowing not to put it in fruit salad.


kingdragonfly

12335 posts

Uber Geek
+1 received by user: 13463

Subscriber

  #3500943 7-Jun-2026 12:09
Send private message

Posted in June 2026, Patrick Boyle is based in Ireland. He's a finance YouTuber normally focused on global markets.

So him speaking on the New Zealand housing market is either extremely good news or extremely bad news.

I guess it depends on which side of the ledger your on.

When a Housing Boom Turns to Bust

Patrick Boyle


wellygary
9197 posts

Uber Geek
+1 received by user: 5819


  #3501045 7-Jun-2026 13:26
Send private message

kingdragonfly: Posted in June 2026, Patrick Boyle is based in Ireland. He's a finance YouTuber normally focused on global markets.

So him speaking on the New Zealand housing market is either extremely good news or extremely bad news.

I guess it depends on which side of the ledger your on.

When a Housing Boom Turns to Bust

Patrick Boyle


Although its seriously superficial , 


He bemoans the $1.8 million dunger house in Avondale..


It may not be the flashest home on the block, but this Great North Rd villa in Avondale sold for close to $2m recently. Photo / Supplied


https://www.nzherald.co.nz/business/personal-finance/investment/auckland-ghost-house-sells-for-18-million-at-auction/4OTU4T6KAI6QR6HDQGWBIP2Z6Q/


But fails to appreciate that it was not the house that had the value buy the land and its future zoned potential..


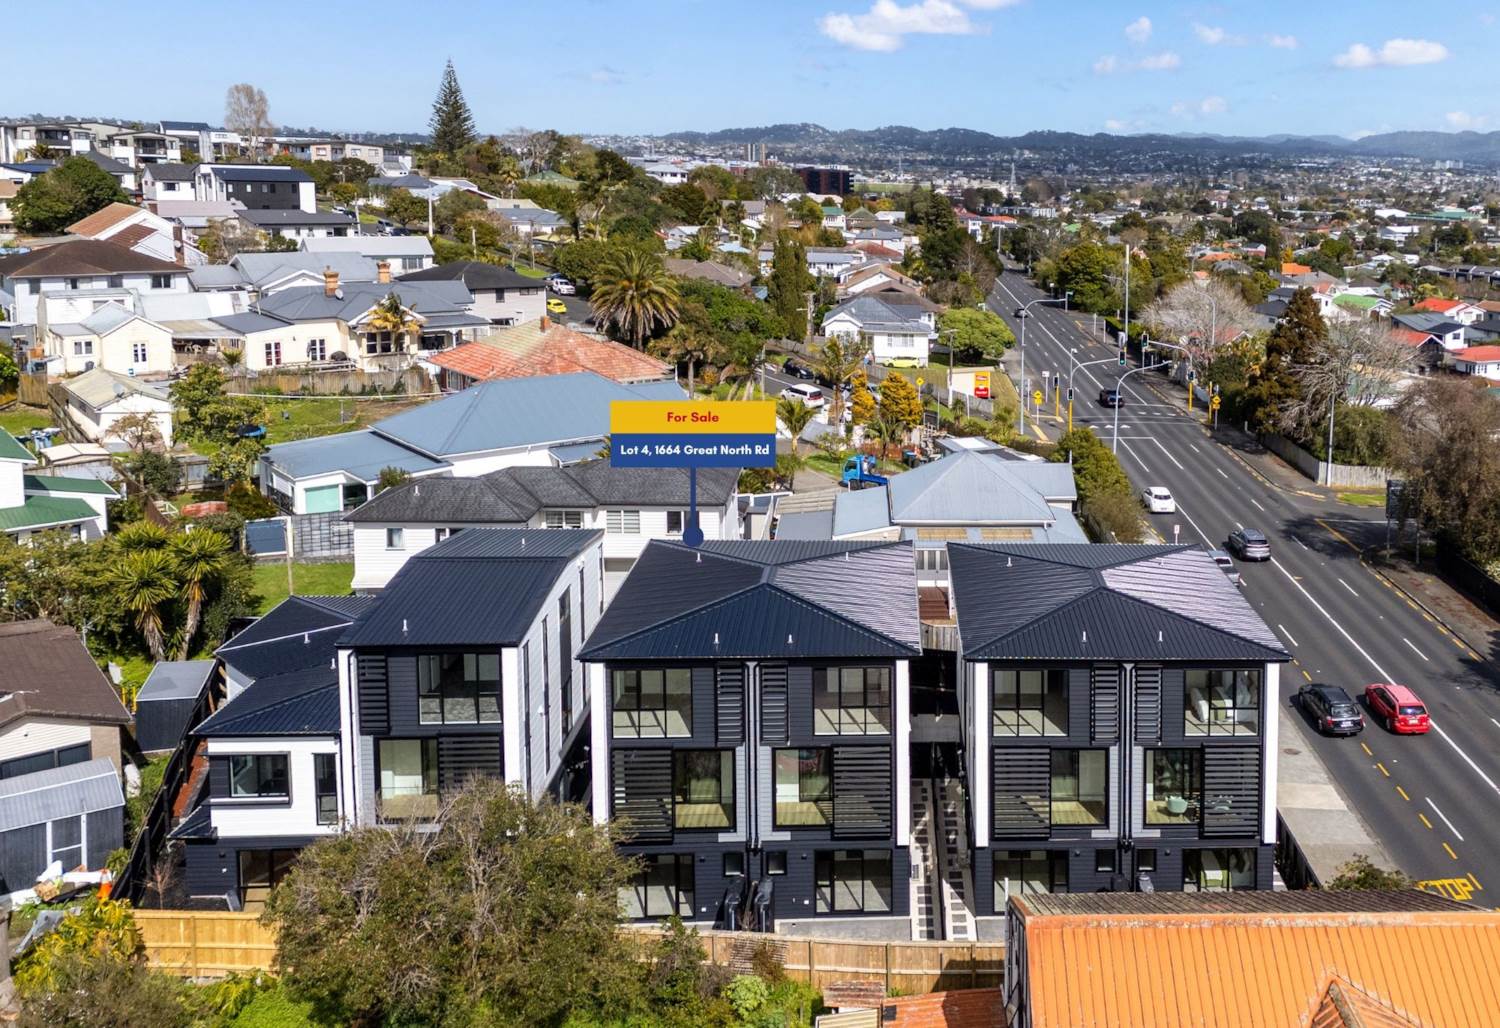
If you check on it now, you find that it now has 5 3 bedroom and 1 duplex townhouses on it,,


https://www.oneroof.co.nz/property/auckland/avondale/6-1664-great-north-road/dpr7p


kingdragonfly

12335 posts

Uber Geek
+1 received by user: 13463

Subscriber

  #3501068 7-Jun-2026 16:47
Send private message

You are correct it is a superficial look from abroad at the New Zealand, and a lesser extent, the US an UK housing bubbles.

I cant figure out where he heard the house was a "dunger" as the media called it a "ghost house" more commonly.

It was sold in 2021, for $1.8m, or $595,000 above council valuation

From what I can see, the land was 936 sq meters / US 0.23 acres / a little less than 0.1 hectares.

The 6 townhouse have a quotable value of about 5.7 million. The land value went from 1.8 million to about 2.6 million.

Not really related, the house was from time when typical suburban home sections in 1940s New Zealand were about one quarter-acre, which is roughly 0.1 hectares.

For the Avondale area, the 1940 sale price expressed in today's purchasing power is no more than $250,000 NZD.

And I have heard others use the nostalgia argument, particularly from young renters. And that would be true false conclusion if you were only looking at historical norms. The price seems high for a single house.

I'm not arguing that the area changed dramatically between 1940 and 2021 Auckland's population grew enormously, infrastructure improved, land became much scarcer relative to demand.

Still for young renters saying "I'll never afford the house my parents bought", it is at least justifiable with the current insane modern land prices are compared to the past.

The market had rational reasons for valuing the site at $1.8m. But ordinary people are still locked out because land values have become detached from what typical wages can support. Incomes have not risen nearly as fast as urban land values.

1 | ... | 169 | 170 | 171 | 172 | 173 | 174 | 175
View this topic in a long page with up to 500 replies per page Create new topic


Geekzone Live »

Try automatic live updates from Geekzone directly in your browser, without refreshing the page, with Geekzone Live now.


Are you subscribed to our RSS feed? You can download the latest headlines and summaries from our stories directly to your computer or smartphone by using a feed reader.